Philippine Banks Post Record Q3 Profit of ₱315.5 Billion
Philippine banks booked their highest third-quarter profit on record, ₱315.5 billion, as elevated interest rates widened lending margins. The snapshot examines what drove the earnings, who benefits, and what the concentration of gains means for borrowers and the wider economy.
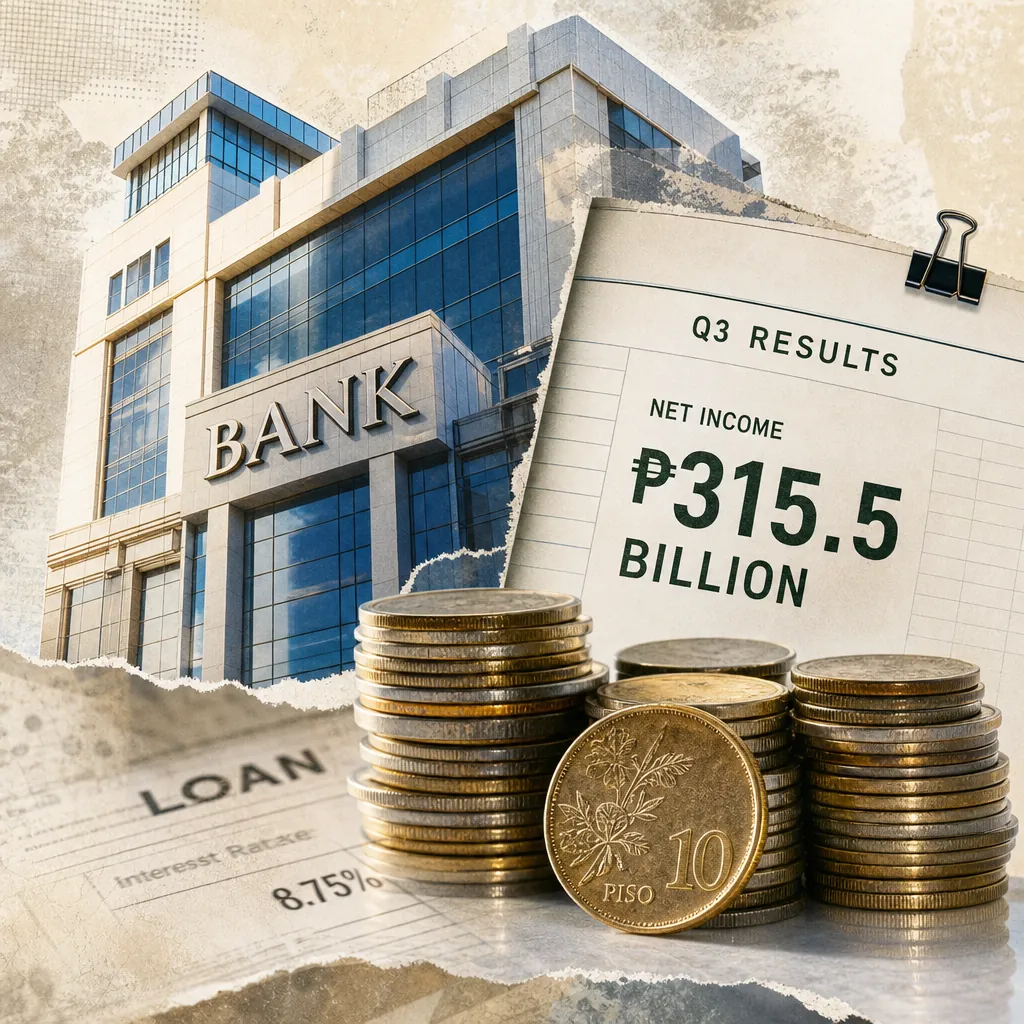
Philippine banks booked a combined net profit of ₱315.5 billion in the three months to end-September, the highest third-quarter earnings the industry has recorded since the Bangko Sentral ng Pilipinas (BSP), the country's central bank, began keeping comparable data in 2008 68. The figure, preliminary BSP data reported on November 2, was up 4.3 percent from the same quarter a year earlier. It is the second consecutive record quarter for the sector, following a record second quarter reported earlier this year 68.
The headline number understates how much of the gain came from one line of business. Net interest income — the money banks earn on loans minus what they pay depositors — rose 14 percent to ₱979 billion, and it did so because borrowing costs stayed high. Total operating income climbed nearly 20 percent to ₱1.2 trillion 68. Non-interest income, the category that includes fees, commissions and trading, actually fell nearly 5 percent to ₱178 billion. Within it, fees and commissions rose 7 percent to ₱144 billion, while trading income jumped more than five times to ₱31.4 billion 68.
The record profit is a story about the cost of money. When the BSP keeps its policy rate elevated to fight inflation, banks pay more for deposits but charge more for loans, and the gap between the two — the margin — widens. For a household or a small business carrying a variable-rate loan, that same margin is the extra peso paid every month. The banks' record quarter and the borrower's heavier repayment are the same transaction seen from opposite ends.
Key themes
- Third-quarter profit of ₱315.5 billion is the highest on record for the period. The combined net income of Philippine banks rose 4.3 percent year on year, according to preliminary BSP data, the strongest third-quarter result since comparable records began in 2008 68.
- Net interest income of ₱979 billion supplied most of the growth. Lending margins widened as borrowing costs stayed elevated, lifting net interest income 14 percent and total operating income nearly 20 percent to ₱1.2 trillion 68.
- Fee and trading income moved in opposite directions. Fees and commissions rose 7 percent to ₱144 billion, but non-interest income overall fell nearly 5 percent to ₱178 billion, even as trading income swelled more than fivefold to ₱31.4 billion 68.
- The record was set against a slowing domestic and global economy. The BSP data described the gains as coming despite economic headwinds at home and abroad, which means the profit growth came from pricing rather than from a surge in lending volume 68.
- Digital payment infrastructure drew new investment. Peppermint Bizmoto Inc., a licensed electronic money issuer, agreed to provide the payment rails for HaveIt, the digital services platform behind the Ride It transport network, which counts more than 6,000 riders 11.
- Small businesses in Cebu were pushed toward digital tools. Grab Philippines brought its digital marketing training program back to Cebu City for a second year, reaching more than 100 local food businesses, in a market where micro, small and medium enterprises make up more than 80 percent of active food merchants on GrabFood 92.
- A water-management seminar put artificial intelligence on the agenda for climate risk. Bangkok Bank and the MIT Sloan ASEAN Office convened a seminar on water management, promoting data and AI to forecast water situations and plan disaster response 1.
How the narratives stack
Dominant: The BSP earnings report is the day's clearest business story. It carries the weight of an official statistical release, it covers the entire banking industry rather than a single company, and it lands as the second consecutive quarterly record. The ₱315.5 billion figure and the 14 percent rise in net interest income are the numbers that will be quoted in boardrooms and in congressional hearings on bank lending. Within the items captured here, this is the only story that reports on the sector as a whole rather than on one firm's partnership or one city's training program.
Counter-narrative: The day's other financial items point in a different direction — toward the unglamorous plumbing of digital finance. Peppermint's agreement to serve as payment rails for HaveIt is a business-to-business deal with no consumer-facing announcement attached, but it matters because it puts a licensed electronic money issuer behind a transport platform with thousands of riders 11. An electronic money issuer is a BSP-licensed institution allowed to hold and transfer funds electronically without being a full bank; the license is what lets a rider pay through an app rather than in cash. Grab's Cebu training session is the same story from the merchant side: small food businesses learning to use AI, branding and social media to reach customers 92. Neither item competes with the earnings report for prominence, but together they describe where the next layer of banking revenue — fees, not margins — is being built.
Emerging: Bangkok Bank's seminar with the MIT Sloan ASEAN Office on water management is the day's most unusual item in this set, and it sits at the edge of the banking conversation rather than inside it 1. The bank's managing director, Chartsiri Sophonpanich, framed water as a basic factor in quality of life, agriculture, industry and national economic activity, and said climate change has made water situations more complex and harder to predict 1. The seminar promoted data and artificial intelligence to assess and forecast water conditions, plan disaster response in advance, and reduce long-term economic and social damage 1. For a Philippine banking audience, the relevance is indirect but real: water risk is credit risk for agricultural and industrial borrowers, and a bank that can model it can price loans better. The item is a Thai bank's initiative, not a Philippine one, and it is a seminar rather than a product or policy.
Under-covered: The borrower's side of the record profit is not covered in the items captured here. The BSP release reports what banks earned; it does not report what households and small businesses paid, how loan growth compared with the rise in margins, or whether lending standards tightened. The 4.3 percent profit growth alongside a nearly 20 percent rise in operating income suggests the gains came disproportionately from pricing rather than volume, but the items reviewed do not include loan-growth figures that would confirm it. That gap is the story a reader trying to understand their own loan statement would most want filled.
Platform insights
- Facebook: The day's most consequential official announcements moved through Facebook first. The Department of Transportation announced the November 4 to 7 traffic disruption in the Shaw-Ortigas area on its Facebook page, warning motorists to take alternate routes as a tunnel boring machine is moved from Pasig City to Mandaluyong City for the Metro Manila Subway project 8. The military's 6th Infantry Division used an official Facebook post to announce the death of an alleged New People's Army instructor in South Cotabato 26. For institutions in this set, Facebook functions as the primary channel for time-sensitive public advisories, and the audience it reaches is the commuting and local-community public rather than the financial readership.
- X: The platform carried the day's political and legal argument in compressed form. A University of Michigan regent used a lengthy X post to describe his concerns about the behavior of the fiancé of Representative Haley Stevens, after Stevens endorsed a Republican candidate she had previously opposed 57. The post became a source for subsequent coverage, which is the pattern that matters for communicators: a single long-form post from a credible institutional figure can set the terms of a story before traditional outlets publish.
- Reddit and YouTube: Neither platform appears in the items captured here. The day's conversation in this set ran through news sites and official social accounts rather than through forum discussion or video.
Key voices and communities
The Bangko Sentral ng Pilipinas: The central bank is the source of the day's dominant number and the institution that sets the policy rate behind the margin story. Its preliminary data release is the authoritative account of industry earnings, and its framing — record profit despite headwinds — is the version that will circulate 68.
Licensed electronic money issuers and platform companies: Peppermint Bizmoto and HaveIt represent a community of non-bank payment providers building the rails beneath consumer apps 11. Their framing is infrastructure and expansion; their audience is merchants, riders and regulators rather than retail depositors.
Small business trainers and platforms: Grab Philippines and the International Trade Centre, the joint agency of the United Nations and the World Trade Organization, are running the digital-skills agenda for micro, small and medium enterprises 92. Their framing is competitiveness and reach; the businesses they train are the customers that banks and payment providers will compete to serve.
Development banks and academic institutions: Bangkok Bank and the MIT Sloan ASEAN Office represent the segment of the industry that frames banking around long-horizon national problems such as water security and climate adaptation 1. Their audience is policymakers and large borrowers, and their currency is research rather than products.
Narrative streams
Record profit of ₱315.5 billion rests on a 14 percent rise in lending margins
The BSP's preliminary data show Philippine banks earning ₱315.5 billion in the third quarter, up 4.3 percent from a year earlier and the highest third-quarter total since 2008 68. The composition matters more than the total. Net interest income reached ₱979 billion, up 14 percent, and total operating income reached ₱1.2 trillion, up nearly 20 percent 68. Non-interest income fell nearly 5 percent to ₱178 billion, with fees and commissions up 7 percent to ₱144 billion and trading income up more than fivefold to ₱31.4 billion 68.
The pattern is a margin story. When the BSP holds its policy rate high to bring inflation down, the rate that banks charge on loans stays elevated while the rate they pay on deposits adjusts more slowly, and the spread between them widens. A 14 percent rise in net interest income against a 4.3 percent rise in total profit means costs and other income lines absorbed much of the margin gain — but the direction is clear. The BSP itself attributed the record to elevated rates boosting margins despite economic headwinds at home and abroad 68.
For the sector, the consequence is a question of durability. Margin-driven profit depends on the policy rate staying high; if the BSP begins cutting rates as inflation eases, the same mechanism runs in reverse and net interest income growth slows. Banks that spent the last two years collecting wider spreads now face the harder work of growing fee income and loan volume. The 7 percent rise in fees and commissions is the line to watch: it is the part of the business that does not depend on the policy rate, and it grew far more slowly than the margin-driven line 68.
For borrowers, the record is a cost. A household with a variable-rate mortgage or a small business with a renewing credit line is paying the wider margin every month. The items reviewed do not report loan growth or default rates, so it is not possible to say from this set whether banks are lending more or simply earning more on the same book. What is confirmed is the earnings; what is observable is that they came from pricing; what remains uncertain is how much of the burden fell on households versus enterprises.
Payment rails for a transport super-app extend digital finance to riders
Peppermint Bizmoto Inc., a licensed electronic money issuer in the Philippines, will serve as the payment infrastructure provider for HaveIt, a digital services platform expanding across transportation and consumer services 11. The centerpiece of HaveIt's ecosystem is Ride It, a transportation network company operating in the Philippines with a network of more than 6,000 riders 11. Under the arrangement, Peppermint processes digital payments across the platform and supports its expansion 11.
The mechanics are worth explaining for a reader outside the industry. A transportation network company is the licensed entity that connects passengers with drivers through an app — the category that ride-hailing services operate under in the Philippines. An electronic money issuer is a BSP-licensed institution that can hold funds in an electronic wallet and move them to another wallet or account without being a full bank. When an issuer provides the "rails" for a platform, it means every fare, top-up and payout on that platform runs through the issuer's licensed system. The issuer earns fees on those flows; the platform gets to operate without building its own payment license and settlement infrastructure.
The read for the sector is about where growth comes from next. The record quarterly profit came from lending margins, a line that rises and falls with the policy rate. Payment processing is a fee business that grows with transaction volume, and it is the segment where non-bank licensed issuers compete directly with banks. A platform with 6,000 riders is small against the national ride-hailing market, but the model — a licensed issuer plugging into a super-app — is how digital payment volume compounds without a bank branch in sight. Banks that want a share of that fee income have to either build similar partnerships or watch licensed issuers take the transaction flow.
Cebu food businesses get digital training as small merchants become the growth market
Grab Philippines brought its Grab Asenso: Digital Diskarte Learning Caravan back to Cebu City for a second year on October 27, gathering more than 100 local food businesses at Baseline Citadines 92. The program, run with the International Trade Centre — a joint agency of the United Nations and the World Trade Organization — offered training in artificial intelligence, digital marketing, branding, content creation, product photography and social media strategy 92. The context the company supplied is the number that matters: micro, small and medium enterprises account for more than 80 percent of active food merchants on GrabFood in Cebu 92.
That share explains why platforms and payment providers are investing in merchant skills rather than only in consumer promotions. A food merchant that can photograph its product, price it for delivery and manage orders digitally generates more transactions, and every transaction carries a fee for the platform and, increasingly, a digital payment for the issuer behind it. The training is a customer-acquisition strategy dressed as a public service, and both descriptions are accurate.
For the banking sector, the Cebu session is a marker of where the next cohort of borrowers sits. Micro, small and medium enterprises are the segment that banks have historically found expensive to serve because the loan sizes are small and the credit information is thin. A merchant that has been trained to run its business on a platform generates a transaction record — sales, refunds, repeat customers — that can substitute for the collateral a small business often lacks. The read for the sector is that the platforms are accumulating the data that banks need to lend to small merchants, and the institutions that partner with those platforms will be able to underwrite the segment at scale before those that do not.
A Thai bank and MIT put water forecasting on the banking agenda
Bangkok Bank Public Company Limited and the MIT Sloan ASEAN Office convened a seminar titled "The Future of Water," bringing researchers from the Massachusetts Institute of Technology to work on Thailand's water management problems 1. The bank's managing director, Chartsiri Sophonpanich, said water management is one of the most important issues for the country's long-term development because water is a basic factor in the quality of life of citizens, agriculture, industry and national economic activity 1. He added that climate change has made water situations more complex and harder to predict, so preparedness requires cooperation and knowledge from many sectors 1. The seminar promoted modern technology, data and artificial intelligence to assess and forecast water conditions, plan disaster response in advance, reduce long-term economic and social damage, and improve monitoring of contamination and water quality 1.
The item is a seminar, not a product launch, and it ran in Thailand rather than the Philippines. Its relevance to the banking sector is in how a large lender treats a physical risk that shows up on its loan book. Agriculture and water-intensive industry are borrowers, and a drought or a flood changes their ability to repay. A bank that can forecast water conditions with better data can adjust its lending and its disaster response before the losses arrive, rather than after. The same logic applies to Philippine banks with agricultural exposure, and the country's own experience with typhoons and El Niño makes the case directly: the Baguio City agriculture committee met on the same day to coordinate typhoon and El Niño damage reporting among its barangay agriculture representatives 94.
For the sector, the read is that climate adaptation is becoming a credit function rather than a corporate social responsibility line. Banks that build forecasting capability into their risk models will price agricultural and industrial loans more accurately; those that do not will absorb the losses when the water arrives. The Bangkok Bank seminar is one institution's bet that the capability is worth building early.
Conversation trajectory
The next BSP data release (observation window: the coming weeks). The third-quarter figures are preliminary. The BSP's finalized data and its next monthly banking indicators will show whether the 14 percent rise in net interest income held through the fourth quarter and whether loan growth accompanied it. If loan growth stayed flat while margins widened, the record profit is a pricing story; if loan volume rose, it is a demand story. The distinction determines whether the sector's earnings are durable into a rate-cutting cycle 68.
The BSP policy meeting cycle (observation window: the next two to three months). The margin mechanism that produced the record quarter runs on the policy rate. Any signal that the BSP is preparing to cut rates will be read by bank investors as the beginning of margin compression, and by borrowers as the beginning of relief. Watch the central bank's statements on inflation for the direction 68.
Payment partnership announcements (observation window: the next quarter). The Peppermint-HaveIt arrangement is the kind of deal that tends to be followed by similar announcements as platforms choose between building payment licenses and renting them. Additional deals involving licensed electronic money issuers and transport or delivery platforms would confirm that the fee-income segment is expanding 11.
Merchant digitization programs (observation window: the next six months). Grab's Cebu training is a recurring program, and its expansion to other cities would indicate that platforms see merchant data as a lending asset. The signal to watch is whether a bank or licensed issuer announces a credit product built on platform transaction data 92.
Trigger events: a BSP rate decision; the release of finalized third-quarter banking data; a major bank's own earnings disclosure, which would confirm or complicate the industry aggregate; and any announcement of a bank-platform lending partnership.
Response guidance
Explain the margin in plain terms when discussing the record profit. A bank communicating its own results should state directly that net interest income rose because the gap between lending and deposit rates widened, and say what that means for a borrower's monthly payment. The number will be read by customers as a cost, and a statement that does not acknowledge the borrower's side will be received as tone-deaf.
Lead with fee income when positioning for a rate-cutting cycle. Banks that want to signal durability should foreground the 7 percent growth in fees and commissions and the payment partnerships behind it, because that line does not depend on the policy rate. Investors and analysts will ask what happens to earnings when margins compress; the answer has to be a specific business line, not a general claim of resilience 68.
Treat payment infrastructure deals as customer-facing news. A licensed issuer providing rails for a transport platform affects riders and drivers directly, even when the announcement is written for business audiences. Communicators should prepare a plain-language explanation of what changes for a rider — how payment works, what happens to a failed transaction, where to complain — before the deal is publicized 11.
Use merchant training programs to build a credit narrative. A platform or bank running digital-skills training for small businesses should say what the training produces beyond skills: a transaction record that can support a loan application. That framing connects the program to the small business's actual constraint, which is access to credit, and it positions the sponsor as a lender rather than a lecturer 92.
Address climate risk as a lending issue. Institutions with agricultural or water-intensive exposure should describe how they model flood, drought and water-quality risk in their credit decisions. The Bangkok Bank seminar shows the framing that large lenders are adopting; Philippine banks with typhoon and El Niño exposure will face the same questions from regulators and investors 1.
Avoid presenting industry aggregates as a single bank's story. The ₱315.5 billion figure is a combined total across all Philippine banks. Any institution citing it should attribute it to the BSP and distinguish it from its own results, because a reader who conflates the two will draw the wrong conclusion about any one bank's performance 68.
See the full picture behind today's signals.
This report draws from Media Meter's MediaWatch, our real-time monitoring engine tracking 2,470+ Philippine sources across print, broadcast, digital, and social. Explore how the platform turns raw coverage into decision-grade intelligence, then see how it's configured for teams like yours — whether you're in PR agencies, corporate comms, government, or marketing.
Want more? Browse our Report Library for sector and crisis intelligence, or request a demo and we'll have your brand set up before the call.
Want this kind of intelligence on your brand?
This brief is built on the same MediaWatch methodology that runs continuously across every brand we monitor. See your competitive landscape, Impact Score, and narrative trajectory in a 30-minute demo.