Digital payments grow 198% as cash-on-delivery holds a quarter
QR Ph and InstaPay transactions rose 198 percent between January 2025 and April 2026, while cash-on-delivery still accounted for nearly a quarter of Philippine e-commerce payment value. A separate survey found Mindanao consumers the most open to borrowing, and a P555.75-million fine against Move It PH put enforcement of transport caps in the spotlight.
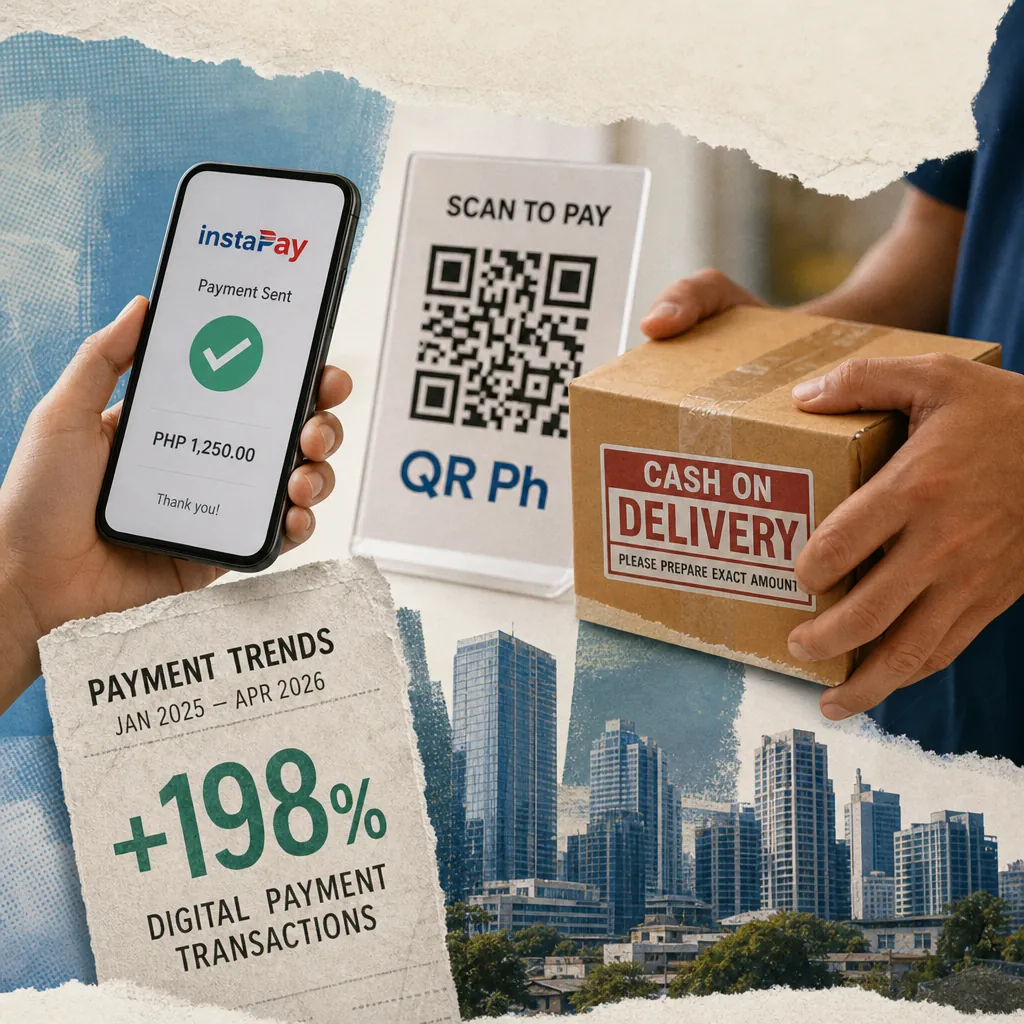
Digital payment transactions on QR Ph and InstaPay grew 198 percent between January 2025 and April 2026, but cash-on-delivery still accounted for nearly a quarter of Philippine e-commerce payment value, according to the Ecommerce Payments Momentum Report 2026 from payments platform Xendit and e-commerce data firm Cube1824. The report, which surveyed 6,000 online shoppers across six Southeast Asian markets including 1,000 from the Philippines, also drew on 25 business-leader interviews and platform transaction data24. The same day's coverage included a TransUnion survey showing 54 percent of Mindanao respondents intend to use credit in the coming months, against a 43 percent national average32, and a Philippine Star column on the Land Transportation Franchising and Regulatory Board's P555.75-million fine against ride-hailing app Move It PH for carrying more riders than its government allocation33. A first-person account from TV Patrol anchor Alvin Elchico described a failed ₱20,000 InstaPay transfer between his BPI account and GCash that was later resolved14. The day's items also included the Philippine National Police reporting eight cybercrime convictions and 144 referred cases in October21, and the Philippine Statistics Authority revising second-quarter GDP growth upward to 2.4 percent from 2.3 percent35.
Key themes
- QR Ph and InstaPay transactions grew 198 percent from January 2025 to April 2026. The figure measures transaction growth on Xendit's platform, not total market volume, and the report says so explicitly24. Cash-on-delivery still accounted for nearly a quarter of e-commerce payment value, meaning the shift to digital is real but incomplete18.
- Mindanao consumers show the strongest appetite for credit. Fifty-four percent of respondents in Mindanao said they intend to borrow or use credit in the coming months, compared with 42 percent in the Visayas and 40 percent in Luzon, and 11 percentage points above the 43 percent national average32. Mindanao also posted the highest Credit Perception Index score at 77 out of 100, up three points from last year32.
- The LTFRB fined Move It PH ₱555.75 million for exceeding its rider allocation. The board found 73,321 active riders against an authorized allocation of 17,746 under the Motorcycle Taxi Pilot Program, and imposed a ₱10,000 administrative fine for each of the 55,575 rider-partners in excess33. The case tests whether platform operators can use internal rider classifications to sidestep government caps.
- A failed InstaPay transfer became a public test of digital payment recourse. TV Patrol anchor Alvin Elchico described transferring ₱20,000 from his BPI account to GCash, finding the money missing from both, and being told by each institution that the problem lay elsewhere14. The amount was later returned, but the episode illustrated how unclear responsibility is when a transfer fails between two regulated institutions.
- The PNP recorded eight cybercrime convictions and 144 referred cases in October. Thirty-four of the referred cases were online libel, the largest category, and 25 involved estafa or swindling under Article 315 of the Revised Penal Code21. The figures cover only cases referred to the PNP Anti-Cybercrime Group, not all cybercrime in the country.
- Second-quarter GDP growth was revised upward to 2.4 percent from 2.3 percent. The Philippine Statistics Authority attributed the revision to wholesale and retail trade, agriculture, and transportation and storage35. First-half average growth remained at 2.6 percent, below the government's 3.5 to 4.5 percent target for the year35.
- BPI Foundation reported reaching over 73,000 students with financial literacy and digital learning programs. The bank's foundation turned over resources in Zamboanga and Basilan with local officials and the Department of Education11. The program places financial education inside the public school system, which is where credit and payment habits begin.
- A Sun Life Bike & Run event drew nearly 2,000 participants to Vermosa Sports Hub in Imus City, Cavite. The inaugural event featured 60-km, 45-km and 15-km bike rides and a 5-km run, with the 45-km category drawing over 800 entries and the 5-km run close to 600538. The event is a brand-adjacent community activity rather than a financial product story, but it reflects how insurers build presence outside the branch.
How the narratives stack
Dominant. The Xendit-Cube report on QR Ph and InstaPay growth is the most consequential item in this set. It carries the largest advertising-equivalent value of any business item captured here, at an estimated ₱736,980 in ad space for the Manila Times version alone24, and it was picked up by at least two outlets1824. The 198 percent growth figure is striking, but the report is careful to say its transaction figures reflect activity on Xendit's platform and should not be read as total market volumes24. The cash-on-delivery share of nearly a quarter is the counterweight: it shows that a large share of online shoppers still pay when the package arrives, which means merchants carry the risk of failed deliveries and returns, and payment providers have a large remaining pool to convert.
Counter-narrative. The TransUnion survey on Mindanao credit appetite runs against the common assumption that borrowing demand is concentrated in Metro Manila and Luzon. Fifty-four percent of Mindanao respondents intend to use credit, 11 points above the national average of 43 percent, and the region's Credit Perception Index score of 77 out of 100 is the highest among the three island groups32. The survey measures stated intention, not actual borrowing, so it is a signal of attitude rather than a forecast of loan volume. Still, for banks and fintech lenders, it points to a market where demand may be building faster than the branch network.
Emerging. The Move It PH fine is the clearest enforcement story in the set. The LTFRB found 73,321 active riders against an authorized allocation of 17,746 and imposed a ₱10,000 fine for each of the 55,575 excess rider-partners, totaling ₱555.75 million33. The company argued that its internal classifications of full-time, part-time, online and offline riders should be considered, but the board rejected that reading33. The case matters beyond one company: it establishes that the regulator will count riders by the government's definition, not the platform's, and that the penalty scales with the size of the overrun. For other ride-hailing and delivery platforms operating under caps, the fine is a warning about how they classify their workers.
Under-covered. The Alvin Elchico InstaPay episode received attention because of his public profile, but the underlying issue — what happens when a transfer fails between two regulated institutions and each says the problem is elsewhere — is a consumer-protection question that affects anyone who moves money between a bank and an e-wallet14. The PNP cybercrime figures, with 34 online libel cases and 25 estafa cases among 144 referrals in October, describe a steady flow of complaints but do not say how many resulted in charges or how quickly cases move21. Both stories sit below the payment-growth headline but describe the friction that determines whether users trust digital channels.
Platform insights
- Facebook. The most shared personal-finance story of the day was Alvin Elchico's video post about his missing ₱20,000, which he said he posted after seeing many others asking what happened14. The post worked because it was a first-person account from a known television anchor, with a specific amount and a resolution. Facebook is where consumer complaints about failed transfers and unauthorized deductions circulate fastest, and where screenshots of customer-service exchanges become the evidence.
- X. The Move It PH fine and the QR Ph growth figures are the kind of policy-and-numbers stories that travel on X among journalists, fintech employees and transport advocates. The 198 percent growth figure and the ₱555.75-million fine are both quotable in a single post, which is how they spread. The risk on X is that the growth figure gets repeated without the caveat that it measures Xendit's platform activity, not the whole market24.
- Reddit. Discussions of cash-on-delivery and e-wallet failures tend to surface on Philippine subreddits as advice threads: which e-wallet reverses a failed transfer fastest, whether to trust a seller who requires a deposit, how to dispute a COD order that arrived damaged. The Xendit-Cube finding that cash-on-delivery still holds nearly a quarter of payment value18 matches what those threads describe: buyers use COD because it shifts the risk of non-delivery to the seller.
- YouTube. Long-form explainers and vlogs on credit scores, loan applications and e-wallet troubleshooting draw steady audiences, and the TransUnion finding that Mindanao respondents are the most credit-receptive32 suggests demand for plain-language content on how credit works. The BPI Foundation's financial literacy program, which reached over 73,000 students11, is the institutional version of the same content.
Key voices and communities
Online shoppers and e-wallet users. The 1,000 Philippine respondents in the Xendit-Cube survey are the core audience for the payment-growth story24. Their behavior — using QR Ph and InstaPay more often while still choosing cash-on-delivery for a large share of purchases — defines the market that payment providers are trying to convert. Alvin Elchico's post gave that group a recognizable case of what can go wrong14.
Credit providers and lenders. TransUnion's regional breakdown gives banks, fintech lenders and credit-card issuers a reason to look at Mindanao differently32. The 54 percent intention figure and the 77-out-of-100 perception score describe a population that is more open to borrowing than the national average, which matters for product design, branch placement and digital onboarding.
Transport regulators and ride-hailing platforms. The LTFRB's fine against Move It PH is the enforcement voice in the set33. The Motorcycle Taxi Pilot Program sets rider allocations, and the board's decision to count riders by its own definition rather than the company's internal categories sets a precedent that other platforms will have to price into their operations.
Law enforcement and cybercrime units. The PNP Anti-Cybercrime Group's October figures — eight convictions and 144 referred cases, including 34 online libel and 25 estafa cases21 — represent the state's response to the fraud and abuse that grow alongside digital transactions. Their case counts are a lagging indicator: they measure what was referred and convicted, not what was attempted.
Financial-literacy advocates and schools. BPI Foundation's program with the Department of Education, which reached over 73,000 students11, is the long-horizon voice in the conversation. Financial habits form early, and the foundation's work in Zamboanga and Basilan puts credit and savings education in front of students who may be the same consumers TransUnion is surveying in Mindanao32.
Narrative streams
QR Ph and InstaPay grew 198 percent while cash-on-delivery held a quarter of payment value
The Xendit-Cube Ecommerce Payments Momentum Report 2026 measured transaction growth on QR Ph and InstaPay from January 2025 to April 2026 and found a 198 percent increase1824. QR Ph is the Bangko Sentral ng Pilipinas' national QR code standard, which lets a customer pay any participating merchant or person by scanning a single code, regardless of which bank or e-wallet holds the account. InstaPay is the central bank's real-time, low-value fund-transfer service, which moves money between institutions within minutes. Together they are the rails on which the shift away from cash is being built. The report's finding that cash-on-delivery still accounted for nearly a quarter of e-commerce payment value18 means the rails are being used more, but a large share of online purchases still settles in cash at the door. The report surveyed 6,000 online shoppers across six Southeast Asian markets, including 1,000 from the Philippines, and interviewed 25 business leaders24. Its transaction figures reflect activity on Xendit's platform and should not be read as total market volumes24. For merchants, the cash-on-delivery share is a cost: failed deliveries, returned goods and cash-handling risk. For payment providers, it is the remaining market. The read for the sector is that the growth in digital transactions is real but the conversion of cash-on-delivery users is the next competitive front, and the providers that reduce the risk of paying online — through clearer refunds, faster dispute resolution and stronger buyer protection — will take share from those that do not.
Mindanao consumers lead the country in credit appetite
TransUnion Philippines' first regional breakdown of its 2026 Credit Perception Index found that 54 percent of respondents in Mindanao intend to use credit in the coming months, compared with 42 percent in the Visayas and 40 percent in Luzon32. The national average was 43 percent, so Mindanao sits 11 percentage points above it32. The index measures how Filipinos view credit based on their knowledge of financial products, trust and overall favorability toward borrowing, and Mindanao scored 77 out of 100, up three points from last year, while the Visayas held at 75 and Luzon trailed32. TransUnion Philippines president and CEO Peter Faulhaber was named in the report32. The survey measures stated intention, not actual loan uptake, so it describes attitude rather than volume. For banks and fintech lenders, the finding suggests that demand for credit may be building fastest in a region where branch networks are thinner and digital onboarding matters more. The read for the sector is that lenders who treat Mindanao as a secondary market may be misreading where the next wave of borrowers is, and that product design — smaller ticket sizes, mobile-first applications, clearer pricing — will determine who captures that demand.
The LTFRB fined Move It PH ₱555.75 million for exceeding its rider cap
The Land Transportation Franchising and Regulatory Board ordered ride-hailing app Move It PH to pay a ₱555.75-million fine for onboarding motorcycle riders beyond its government-authorized cap33. The board found 73,321 active riders across Metro Manila, Cebu and Cagayan de Oro as of May, against an authorized allocation of 17,746 under the Motorcycle Taxi Pilot Program33. It imposed a ₱10,000 administrative fine for each of the 55,575 rider-partners in excess of the allocation and flagged the company for disregarding a one-year moratorium on new rider onboarding33. Move It argued that it uses internal classifications — full-time and part-time, online and offline, riders working more or fewer than eight hours a day — but the board maintained that the authorized number applies to rider-partners as the government defines them33. The Motorcycle Taxi Pilot Program is the government's framework for allowing motorcycles to carry passengers for hire, which was long restricted; the rider cap is meant to keep the pilot within a size the regulator can monitor. The case matters for every platform operating under a cap: the penalty scales with the size of the overrun, and the regulator has rejected the argument that internal categories change the count. The read for the sector is that compliance now depends on the government's definition of a rider, not the platform's, and that platforms with large numbers of part-time or intermittently active riders face the most exposure.
A failed InstaPay transfer put digital payment recourse in public view
TV Patrol news anchor Alvin Elchico posted a video describing a ₱20,000 transfer from his BPI account to GCash that did not arrive14. He said the amount was deducted from his BPI account but did not appear in his GCash account, and that when he called both institutions, each said the problem was not on its side and pointed to InstaPay14. He added that he checked social media and found many others asking what had happened and whether there was any development14. The amount was later returned14. The episode is a consumer-protection story about what happens when a transfer fails between two regulated institutions: the customer is left to coordinate between them while the money sits in an unresolved state. InstaPay transfers are designed to settle in real time, but failures can occur when one institution's system does not confirm the transaction, and the resolution process depends on the institutions' back-office coordination. For banks and e-wallets, the reputational risk is concentrated in these moments: a customer who cannot get a clear answer from either side may stop using the channel. The read for the sector is that the growth of digital payments depends on recourse as much as on speed, and that institutions which publish clear timelines and single points of contact for failed transfers will earn trust that marketing cannot buy.
Cybercrime referrals show fraud and online libel dominating complaints
The Philippine National Police recorded eight cybercrime convictions and 144 referred cases in October, according to the PNP Anti-Cybercrime Group21. Thirty-four of the referred cases were online libel, the largest category, and 25 involved estafa or swindling under Article 315 of the Revised Penal Code21. Another 14 cases combined online libel and unjust vexation21. PNP chief Gen. Jose Melencio Nartatez Jr. reminded the public to be vigilant online21. The figures cover cases referred to the Anti-Cybercrime Group, not all cybercrime in the country, and the conviction count reflects cases that completed the legal process, which typically takes longer than a month. For digital payment providers, the estafa cases are the relevant signal: they describe fraudulent transactions and misuse of digital platforms, which are the same risks that make some shoppers prefer cash-on-delivery18. The read for the sector is that fraud enforcement is a slow-moving backstop, and that payment providers cannot rely on prosecution to deter fraud; they need prevention at the point of transaction, through verification, limits and monitoring.
GDP revision and financial-literacy programs set the background
The Philippine Statistics Authority revised second-quarter GDP growth upward to 2.4 percent from a preliminary 2.3 percent, with upward revisions in wholesale and retail trade, agriculture, forestry and fishing, and transportation and storage35. First-half average growth remained at 2.6 percent, below the government's 3.5 to 4.5 percent target for the year35. The revision is small, but it describes an economy growing more slowly than the government planned, which affects everything from credit demand to payment volumes. Separately, BPI Foundation reported reaching over 73,000 students nationwide with financial literacy and digital learning programs, with a turnover ceremony in Zamboanga and Basilan attended by local officials and the Department of Education11. The Department of Education is the government agency that runs the public school system, and its involvement places financial education inside the curriculum rather than in standalone seminars. The read for the sector is that financial literacy is being delivered through schools, which is where credit and payment habits form, and that banks which build that relationship early may see it in customer acquisition later.
Conversation trajectory
Watch the next Xendit-Cube or BSP payment-volume release (observation window: next quarterly report). The 198 percent growth figure covers January 2025 to April 2026, and the next update will show whether the pace held through the rest of 2026. The key number to watch is the cash-on-delivery share: if it falls below a quarter, the conversion is accelerating; if it holds, the remaining pool is stickier than the growth figure suggests1824.
Watch the LTFRB's next enforcement action against a ride-hailing or delivery platform (observation window: next 4–6 weeks). The Move It PH fine establishes that the board will count riders by its own definition and fine per excess rider33. Other platforms operating under the Motorcycle Taxi Pilot Program or similar caps will be watching whether the board applies the same method, and whether any platform appeals the ruling. A second fine would confirm the precedent; an appeal would extend the uncertainty.
Watch TransUnion's next Credit Perception Index release and any regional lending data (observation window: next 3–6 months). The Mindanao finding is based on stated intention32. Actual loan growth data from banks and fintech lenders will show whether the intention converts. If Mindanao lending grows faster than Luzon and the Visayas, the survey will have been an early signal; if not, the gap between attitude and behavior will be the story.
Watch the PNP Anti-Cybercrime Group's monthly case counts (observation window: next monthly release). The October figures — eight convictions and 144 referrals, with 34 online libel and 25 estafa cases21 — set a baseline. A rising estafa count would suggest fraud is growing with digital payment volume; a rising conviction count would suggest the justice system is catching up. Either way, the monthly release is the checkable indicator.
Trigger events. A publicized failure of a major e-wallet or bank transfer system would push recourse to the top of the conversation, as the Elchico episode did14. A Bangko Sentral ng Pilipinas circular on failed-transfer resolution or on cash-on-delivery would change the rules for both providers and merchants. A new entrant in the motorcycle taxi pilot or a change to the rider cap would reopen the Move It PH question33.
Response guidance
Payment providers: publish clear recourse timelines for failed transfers. The Elchico episode showed that customers do not know which institution is responsible when a transfer fails between a bank and an e-wallet14. A published timeline — how long a reversal takes, who to call, what information to have ready — reduces the chance that a single failure becomes a public complaint. Put it where customers look during a problem: the app, the website and the customer-service line.
Merchants: treat cash-on-delivery as a cost line, not a default. The Xendit-Cube finding that cash-on-delivery still holds nearly a quarter of payment value18 means many merchants are absorbing failed deliveries and returns. Offering a small incentive for prepayment, or a clear buyer-protection policy for online payments, can shift the mix without forcing customers who distrust online payment to abandon the purchase.
Lenders: look at Mindanao as a growth market with different product needs. The TransUnion finding that 54 percent of Mindanao respondents intend to use credit32 describes demand that may not be served by branch-based products. Smaller ticket sizes, mobile onboarding and plain-language pricing are the obvious adaptations. The BPI Foundation's school-based financial literacy work11 is a reminder that the same market is being educated early.
Ride-hailing and delivery platforms: audit rider counts against the government definition. The LTFRB's ₱555.75-million fine against Move It PH33 shows that internal classifications do not change the authorized count. Platforms should reconcile their active-rider lists with the regulator's definition before the next inspection, and should be prepared to explain how part-time and intermittent riders are counted.
Communicators: avoid repeating the 198 percent figure without its scope. The growth figure measures Xendit's platform activity, not total market volume24. Using it as a market-wide number invites correction and undermines the credibility of the broader message. Pair it with the cash-on-delivery share to give a complete picture: digital payments are growing, and a large share of e-commerce still settles in cash.
Financial institutions: coordinate on fraud prevention rather than competing on blame. The PNP's 25 estafa referrals in October21 and the Elchico transfer failure14 both point to the same problem: when something goes wrong, the customer is left to navigate between institutions. Shared standards for verification, transfer confirmation and dispute handling would reduce the number of cases that become public complaints.
See the full picture behind today's signals.
This report draws from Media Meter's MediaWatch, our real-time monitoring engine tracking 2,470+ Philippine sources across print, broadcast, digital, and social. Explore how the platform turns raw coverage into decision-grade intelligence, then see how it's configured for teams like yours — whether you're in PR agencies, corporate comms, government, or marketing.
Want more? Browse our Report Library for sector and crisis intelligence, or request a demo and we'll have your brand set up before the call.
Want this kind of intelligence on your brand?
This brief is built on the same MediaWatch methodology that runs continuously across every brand we monitor. See your competitive landscape, Impact Score, and narrative trajectory in a 30-minute demo.