Money mule fraud exposure hits P603B, peso rebounds
A joint white paper by IDfy Philippines and CIBI Information Inc. estimates P603 billion in annual fraud exposure from money mule accounts, while the peso recovers from a record low and the stock market braces for the central bank's rate decision and GCash's listing.
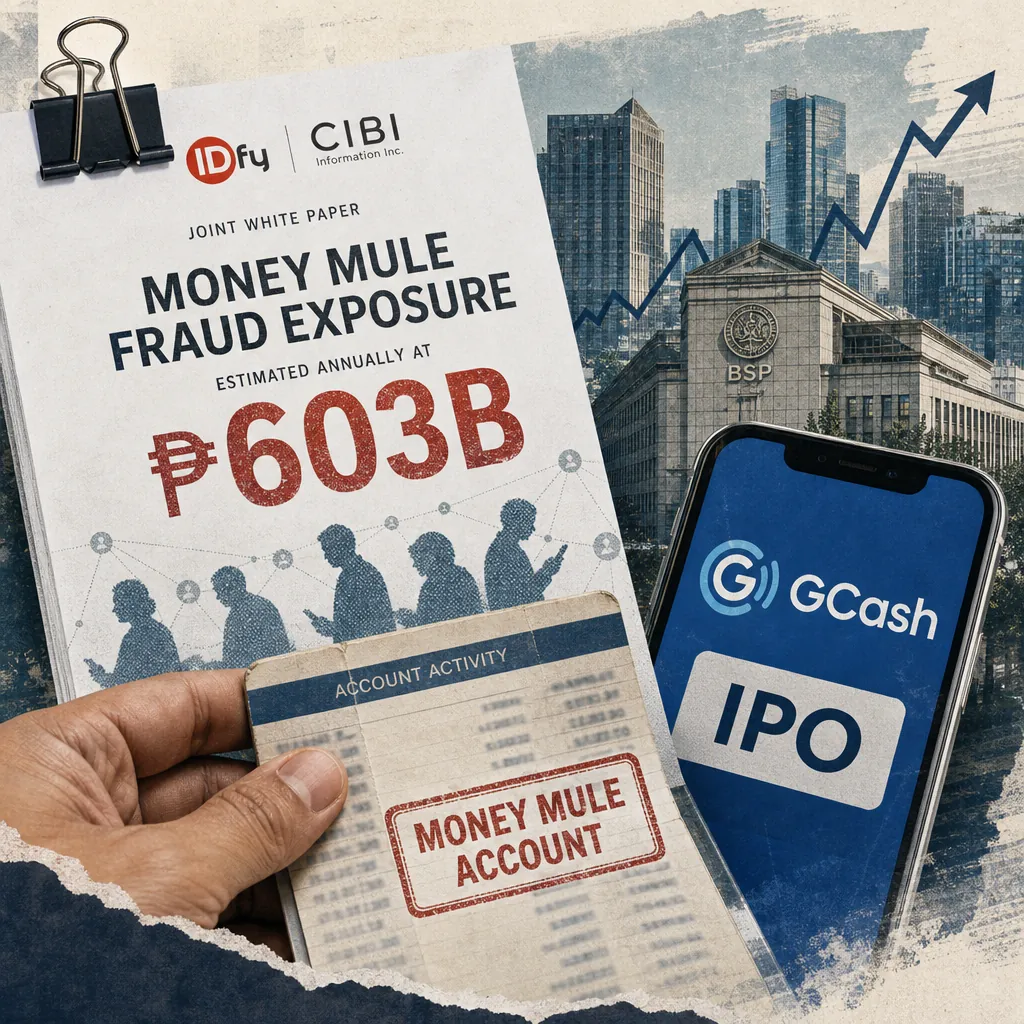
A white paper from a trust-technology firm and a credit-reporting agency put a number on one of the country's fastest-growing financial crimes: up to ₱603 billion a year in exposure to fraud routed through money mule accounts, drawn from 2025 payment data across the central bank's two real-time payment systems3032. The estimate landed the same weekend the peso clawed back from a record low against the dollar and the stock market headed into a week shaped by an expected interest-rate hike and the listing of the country's dominant e-wallet operator1033.
The mule study, "Mule Hunting: Are We Chasing Ghosts?", was released jointly by IDfy Philippines and CIBI Information Inc. and reported by The Manila Times and Head Topics3230. It describes accounts used to receive and move money obtained through digital scams — sometimes opened knowingly by the account holder, sometimes by people tricked into participating, sometimes taken over outright32. IDfy country head Raghu Chandrasekhar said technology alone cannot solve the problem and called for public awareness alongside the safeguards required under the Anti-Financial Account Scamming Act, or Afasa, the law that obliges banks and e-wallet providers to police account takeovers and scam transactions32. The same firm told the Daily Tribune it plans to expand into insurance and telecommunications client onboarding next year, building on work with more than 10 Philippine organizations including leading banks and thrift banks56.
The peso closed at ₱62.985 per dollar on Friday, 7.5 centavos stronger than Thursday's ₱63.06, after touching an intraday low of ₱63.23, according to Bankers Association of the Philippines data10. Trading volume rose to $1.598 billion from $1.502 billion the day before10. The Philippine Stock Exchange index finished the week at 5,782.70, up 1.43 percent week-on-week for a second straight weekly gain, though foreign investors were net sellers of ₱1.41 billion over the week, according to online brokerage 2TradeAsia.com33. Both the peso and the index now wait on the Bangko Sentral ng Pilipinas, whose policy-setting Monetary Board meets Oct. 22, with a 25-basis-point rate increase increasingly expected after September inflation came in at 7.2 percent33.
Key themes
- Mule-account fraud exposure estimated at ₱603 billion a year. The IDfy–CIBI white paper puts the annual figure on funds moved through mule accounts across PESONet and InstaPay, the central bank's two real-time payment rails, based on 2025 data3032. The number measures estimated exposure, not confirmed losses.
- The peso recovered 7.5 centavos after hitting a record intraday low. It closed Friday at ₱62.985 per dollar against Thursday's ₱63.06, but the weighted average rate still rose to ₱63.068 from ₱63.049, meaning the day's average trade was weaker even as the close strengthened10.
- The stock index gained 1.43 percent week-on-week into two catalysts. The PSEi's second consecutive weekly gain came on bargain hunting, with the BSP's Oct. 22 decision and the Mynt (GCash) debut as the week's drivers3370.
- A 25-basis-point hike is the base case after 7.2 percent September inflation. 2TradeAsia called it the minimum adjustment needed, and Unicapital Securities expects trading to take its cue from the BSP's guidance on inflation and the currency3370.
- Afasa compliance is now a board-level cost for banks and e-wallets. The law requires financial institutions to detect and block account takeovers and scam-linked transfers; the mule study argues that compliance spending must be paired with customer education32.
- IDfy is moving from banks into insurance and telecom onboarding. The verification firm says it will target at least one leading institution in each sector next year, a sign that identity checks are spreading beyond banking as scam risk grows56.
- Davao police warned borrowers off illegal lenders ahead of the holidays. The Police Regional Office-Davao Region flagged excessively high interest, missing paperwork, threats and pressure to take new loans as warning signs, citing complaints about online lending platforms logged by the Securities and Exchange Commission's Davao office8.
- A ₱55-million Antipolo house tour drew 9,869 views on YouTube. The Homescape Realty listing for a furnished five-bedroom home with a 5-kilowatt solar setup and voice-command system drew 211 likes and no comments, a small sample that says more about listing format than about the property market1.
How the narratives stack
Dominant. The mule-fraud estimate carried the most consequence in the items reviewed here. It arrived in two versions — The Manila Times' business-page treatment and Head Topics' syndicated copy — and it attaches a peso figure to a crime that until now has been described mostly through anecdote3230. The peso and stock-market stories ran alongside it with their own hard numbers: a 7.5-centavo recovery, a 1.43 percent weekly index gain, ₱1.41 billion in net foreign selling1033. Within this captured set, the financial story is the one with the widest spread of concrete figures.
Counter-narrative. The peso's Friday recovery reads as good news, but the weighted average exchange rate rose to ₱63.068 from ₱63.049, and the currency still sits near its weakest levels on record10. The stock index's two-week winning streak came with subdued trading activity and foreign investors selling more than they bought33. Both are recoveries inside a weaker trend, and the coverage says so.
Emerging. Identity verification as a growth business is the quieter thread. IDfy's plan to move into insurance and telecommunications onboarding next year, disclosed in the Daily Tribune, suggests the compliance burden created by Afasa is generating a market of its own56. The Davao police advisory on illegal lenders points at the same consumer-protection gap from the borrowing side8.
Under-covered. The Davao lending warning drew a single item in this set and no national pickup, even though it concerns the same households the mule study says are most exposed to scam recruitment832. The connection between predatory lending and mule recruitment — a borrower pressured into lending out an account — is not drawn explicitly in any of the items reviewed.
Platform insights
- YouTube. The only social item in this set is a Homescape Realty house tour that drew 9,869 views and 211 likes as of Oct. 18, with no comments1. The like-to-view ratio is roughly one in 47, and the absence of comments means there is no visible buyer discussion to read. A single listing cannot establish a market trend in smart-home pricing, and the writeup does not say whether the post was boosted.
- Facebook, X and Reddit. No posts from these platforms appear in the material reviewed for this window, so there is no engagement evidence to compare across them.
Key voices and communities
Fraud-prevention and identity-verification firms. IDfy Philippines and CIBI Information Inc. produced the mule study, and IDfy's Raghu Chandrasekhar is the most-quoted voice in the financial coverage, framing the problem as one that requires awareness as much as technology3256. Their commercial interest is in selling verification services, which readers should weigh when reading their estimate.
Market analysts and brokerages. 2TradeAsia.com and Unicapital Securities set the terms of the week's market expectations, with 2TradeAsia's Jonathan Ravelas attributing the peso's weakness to "a series of unfortunate events" including higher US rate-hike odds and geopolitical risk103370.
The Bangko Sentral ng Pilipinas. The central bank is the actor everyone else is waiting on. Its Monetary Board sets the benchmark interest rate, and its Oct. 22 decision will move both the currency and the stock index3370.
Regional police and the SEC. The Police Regional Office-Davao Region and the Securities and Exchange Commission's Davao office are the consumer-protection voices on lending, warning borrowers directly rather than through the financial press8.
Narrative streams
Mule accounts carry an estimated ₱603 billion a year in fraud exposure
The white paper examined 2025 payment data across PESONet and InstaPay — the central bank's two real-time fund-transfer systems, one for batch interbank transfers and one for instant retail payments — and concluded that mule accounts are a significant channel for moving scam proceeds into the formal financial system30. A money mule account is a bank or e-wallet account used to receive and pass on illicit funds; the holder may be a willing participant, a person deceived into handing over access, or a victim of account takeover32. The ₱603 billion figure is an estimate of annual exposure, not a count of confirmed losses, and it comes from two firms with a commercial stake in fraud prevention.
Chandrasekhar's argument is that the Anti-Financial Account Scamming Act, which requires banks and e-wallet providers to guard against account takeovers and scam transactions, sets a floor rather than a ceiling. "While technical safeguards and regulatory compliance under Afasa are essential, technology alone cannot solve a problem" of this kind, he said, calling for public awareness alongside the rules32. For banks, e-wallet operators and payment processors, the practical consequence is that customer education becomes part of compliance rather than a marketing add-on: an account holder who understands why a stranger wants to borrow their account is the cheapest fraud control available. For consumers, the read is blunter — lending out an account, even to a relative, can make the holder a link in a chain that the law now treats as a criminal one.
The peso recovers from a record low while the average rate keeps weakening
The peso's Friday session traced a full arc: it opened at ₱63.03, weakened to ₱63.23, then recovered to close at ₱62.985, 7.5 centavos stronger than Thursday's ₱63.0610. The weighted average rate, which averages every trade rather than just the closing one, rose to ₱63.068 from ₱63.049 — so the day's typical transaction was slightly weaker even as the final print improved10. Volume rose to $1.598 billion from $1.502 billion10.
Ravelas of Reyes Tacandong & Co. attributed the pressure to "a series of unfortunate events," citing a higher probability of a US interest-rate hike after elevated inflation readings in both the US and the Philippines, geopolitical risks and declining gross international reserves10. For importers and households buying dollar-priced goods, a peso near ₱63 means the exchange rate itself is now a source of inflation, which is why the central bank's Oct. 22 meeting matters beyond the stock market. A rate increase raises borrowing costs across the economy but supports the currency by making peso deposits more attractive.
The stock market waits on the BSP and the GCash listing
The PSEi closed at 5,782.70, up 1.43 percent week-on-week, its second consecutive weekly gain, helped by bargain hunting and easing global bond yields3370. The recovery is thin: trading activity stayed subdued and foreign investors sold ₱1.41 billion more than they bought over the week, according to 2TradeAsia33. Two events dominate the week ahead — the BSP's Oct. 22 policy decision and the market debut of Mynt Inc., the operator of GCash, the country's largest e-wallet3370.
Unicapital Securities head of research Wendy Estacio-Cruz said investors are also watching September balance-of-payments data due Oct. 19 for direction on foreign-exchange flows and interest rates70. The balance of payments records a country's transactions with the rest of the world, and a deficit there drains reserves and pressures the peso. For listed companies and their investors, the week's combination — a possible rate hike, a large new listing and a weak currency — sets the cost of capital for the rest of the year. A GCash listing also gives the public market its first direct exposure to the digital payments business that the mule study says is being exploited.
Identity verification expands from banks into insurance and telecoms
IDfy Philippines works with more than 10 local organizations, including leading banks and thrift banks, and plans to court insurance companies and telecommunications firms for customer onboarding next year, Chandrasekhar told the Daily Tribune56. The company's pitch is that verification speeds up account opening while filtering out fraud, and its expansion plans assume that regulators will keep raising the bar on who must check identities and how.
For insurers and telcos, the change is operational: SIM registration and know-your-customer rules already require identity checks, and a fraud wave that moves through e-wallets will eventually reach any account that can receive and forward money. For consumers, faster onboarding cuts both ways — it shortens the wait for a legitimate account and shortens the time a scammer needs to open a fraudulent one. The sector's read is that identity infrastructure is becoming a shared utility across finance, telecoms and insurance, and the firms that build it will be selling into every regulated industry that touches money.
Davao police warn borrowers off illegal lenders as the holidays approach
The Police Regional Office-Davao Region advised the public to borrow only from legitimate, authorized lenders, listing excessively high interest rates, a lack of paperwork, threats and intimidation, and pressure to take out additional loans as warning signs of illegal lending8. The advisory is timed to the holiday season, when households face higher expenses and are more likely to borrow8. The Securities and Exchange Commission's Davao office has logged complaints involving online lending platforms and financing schemes, according to its director, Lawyer Katrina Jamilla Ponco-Estares8.
For lenders operating legitimately, the advisory is a reminder that the online lending segment's reputation is being set by its worst actors, and that collection practices are the point where the difference shows. For borrowers, the practical test is paperwork: a lender that will not put terms in writing is not a lender the police will be able to help recover money from. The connection to the mule problem is direct even if no item draws it — a borrower under collection pressure is a prime target for someone offering cash for the use of an account.
A ₱55-million Antipolo listing tests smart-home features as a selling point
Homescape Realty listed a five-bedroom house and lot in Mission Hills, Havila, Antipolo City at ₱55 million, marketed as a fully furnished "smart luxury" home with a 380-square-meter floor area on a 308-square-meter lot, a private pool, a 5-kilowatt solar setup and a voice-command system1. The YouTube tour drew 9,869 views and 211 likes as of Oct. 18, with no comments1. The listing targets buyers wanting a gated suburban home with access to Ortigas Avenue Extension and C-51.
One listing is not evidence that Philippine property buyers now price smart-home features above location, and the writeup itself notes that a single post gives no sign of how the market is responding1. For developers and agents, the useful signal is format rather than price: video tours with feature detail are being used to generate inquiries, and solar and automation claims in a listing are assertions a buyer should verify with the developer before treating them as standard. For the residential market, the more durable trend is the one running through the other stories — the cost of borrowing. A rate hike on Oct. 22 raises monthly payments on housing loans, and at ₱55 million the Antipolo listing sits at the end of the market most sensitive to financing costs.
Conversation trajectory
Oct. 19 — balance of payments data. September balance-of-payments figures are due, and Unicapital's Estacio-Cruz has flagged them as a guide to foreign-exchange flows70. A wider deficit would reinforce the peso's weakness and raise the odds of a hike; a narrower one would give the central bank room to hold. Watch the peso's close against ₱63.
Oct. 22 — BSP policy decision. The Monetary Board meets with a 25-basis-point increase widely expected after 7.2 percent September inflation33. A hike of that size is likely already priced into the stock index; a larger move or hawkish guidance would pressure both the currency and equities, while a hold would weaken the peso further. The central bank's statement on the currency will matter as much as the rate itself.
This week — Mynt (GCash) market debut. The listing gives the public market its first direct stake in the e-wallet business and will be read as a test of investor appetite for Philippine technology assets3370. A strong debut would pull attention toward digital finance; a weak one would leave the mule-fraud story as the sector's main headline.
Next 4–6 weeks — holiday lending season. The Davao police advisory is timed to the run-up to Christmas, when borrowing rises8. Complaints to the SEC's regional offices and police advisories from other regions are the checkable signals of whether illegal lending is spreading.
Trigger events. A confirmed mule-fraud case prosecuted under Afasa would move the story from estimate to precedent. A BSP statement specifically naming mule accounts or scam transfers would signal that the central bank is treating the ₱603 billion figure as a policy problem rather than an industry talking point.
Response guidance
Banks and e-wallets: treat customer education as a compliance line item. Afasa requires safeguards against account takeover and scam transfers; the mule study argues those safeguards fail without customers who understand why an account should never be lent or sold32. Fund awareness campaigns at the same level as detection technology and measure them by reported scam attempts, not impressions.
Payment processors: publish what you block. The ₱603 billion figure is an estimate of exposure, and the industry's credibility problem is that the public cannot see the difference between exposure and loss30. Releasing aggregate counts of blocked mule transfers, with the methodology stated, gives regulators and reporters a real number to work with.
Lenders and fintechs: separate legitimate credit from predatory collection. The Davao advisory lists threats, missing paperwork and pressure to re-borrow as markers of illegal lending8. Legitimate lenders should make written terms and collection standards visible, because borrowers under pressure are the recruiting pool for mule schemes.
Insurers and telcos: prepare for identity checks to tighten. IDfy's expansion plans assume onboarding scrutiny will keep rising in both sectors56. Building verification into account opening now is cheaper than retrofitting it after a fraud incident.
Property developers and agents: verify feature claims before repeating them. A listing that advertises solar and automation should be able to show the specifications, and a single video tour is not a market trend1. Buyers comparing listings should ask for the installed capacity and the warranty, not the marketing language.
Communicators covering the peso and the market: state the baseline. A 7.5-centavo recovery and a 1.43 percent weekly gain are moves inside a weaker trend, and the weighted average rate and net foreign selling are the figures that show it1033. Report the close and the average together.
See the full picture behind today's signals.
This report draws from Media Meter's MediaWatch, our real-time monitoring engine tracking 2,470+ Philippine sources across print, broadcast, digital, and social. Explore how the platform turns raw coverage into decision-grade intelligence, then see how it's configured for teams like yours — whether you're in PR agencies, corporate comms, government, or marketing.
Want more? Browse our Report Library for sector and crisis intelligence, or request a demo and we'll have your brand set up before the call.
Want this kind of intelligence on your brand?
This brief is built on the same MediaWatch methodology that runs continuously across every brand we monitor. See your competitive landscape, Impact Score, and narrative trajectory in a 30-minute demo.